Key Takeaways:
- AI in finance is moving from rule-based automation to agentic AI.
- Wealth management, insurance, FinTech, and RegTech each gain distinct value from AI.
- Scaling AI starts with unified data and API layers, not models.
- Bias testing, explainability, and human oversight keep AI trustworthy for regulators.
- Measure AI returns beyond cost savings, including revenue and customer lifetime value.
- Sensitive data, legacy systems, model errors, and cyber threats stall AI pilots.
Nowadays, everyone is talking about AI in financial services. And most of what they are saying is either too optimistic or too alarming to be useful.
The optimistic version promises a frictionless future where algorithms handle everything, and humans are freed to focus on strategy. The alarming version warns of runaway systems, job losses, and data breaches waiting to happen. Both versions are missing something important: nuance.
The reality of artificial intelligence in financial services is more complicated and more interesting than either camp admits. It is delivering genuine, measurable value in specific areas. It is also creating new risks that many institutions are not adequately prepared for. Today, “fewer than one in four banks1 are ready for the AI era.”
For CIOs, CTOs, CDOs, and the leaders funding these initiatives, the debate is no longer whether artificial intelligence belongs in the enterprise. The real challenge is scaling it across wealth, insurance, payments, and compliance without losing control over risk, cost, or customer trust.
This blog looks at where AI is creating value in each vertical and lays out a five-step framework for building an AI strategy for financial institutions that scales beyond pilots. It also talks about the risks that need urgent attention.
The Shift From Task Automation to Autonomous Financial Ecosystems
Present-day enterprises use machine learning, natural language processing, and generative AI technologies in wealth management, capital markets, insurance, and banking. But very few institutions started there. Most began with narrow automation projects. The distance between those early efforts and what AI can do today explains the urgency driving leaders now.
1. From Rule-Based Systems to Agentic and Multimodal AI
Financial technology ran on fixed rules for many decades. To give an example, a transaction above a set threshold triggered a manual review. Machine learning replaced many such rules with models that learn from past patterns. The arrival of generative AI in financial services then added the ability to read and write documents and answer questions in plain language.
The newest stage is agentic AI. These systems plan and carry out multi-step tasks on their own. Multimodal models extend that reach to images, voice, and scanned documents. These technologies thus change AI from a single-task tool into a coordination layer working across operations.
2. How Widely Are Financial Institutions Adopting AI?
AI use has moved from small experiments to everyday use. In NVIDIA’s 2026 State of AI in Financial Services survey2 of more than 800 industry professionals, 65% said their company actively uses AI, up from 45% a year earlier. The same survey found that 42% are using or assessing agentic AI and 21% have deployed AI agents.
JPMorgan Chase CEO Jamie Dimon described the scale of this change in his letter to shareholders:
“The pace of adoption will likely be far faster than prior technological transformations, like electricity or the internet. AI will affect virtually every function, application, and process in the company.”
3. What Business Value Does AI Deliver?
AI in financial services fundamentally changes what institutions can achieve. It lowers costs, improves decisions, and delivers services built around the customer. These gains fall into five areas:
- A. Faster Work with Fewer Errors: Processes that used to take days, like compliance checks or account onboarding, can now happen in hours or minutes. AI handles the repetitive, rule-based work with a consistency that human teams simply cannot match at scale.
- B. Decisions Backed by More Data: Whether it is a credit call, a fraud flag, or a trade, AI can pull from far more data sources than any analyst working manually.
- C. Personalization at Scale: Instead of segmenting customers into broad buckets, institutions can tailor products, communications, and recommendations to the individual in real time.
- D. Lower Cost of Compliance: AI-powered RegTech tools automate monitoring and reporting functions that once required large teams.
- E. Improved Risk Management: Traditional risk models look backwards. AI-driven risk systems look at what is happening right now and flag issues before they become problems.
4. Legacy Infrastructure vs. AI-Native Enterprise Ecosystem
The benefits that we just discussed depend on the foundation that sits below them. The table below shows how an AI-native operating model differs from the legacy setup that a large number of institutions still run.
| Dimension | Legacy Financial Infrastructure | AI-Native Enterprise Ecosystem |
|---|---|---|
| Data | Siloed in product-specific core systems | Unified, governed, and available through APIs |
| Decision-making | Static rules and periodic batch reviews | Real-time models with human oversight on high-stakes calls |
| Risk monitoring | Based on past reports | Continuous, using live market and customer signals |
| Compliance | Manual checks and sampled reviews | Automated monitoring with full audit trails |
| Customer experience | Segment-based products and generic outreach | Individual recommendations delivered in real time |
| Pace of change | Months to release a new rule or product | Models retrained as market conditions shift |
How AI Is Transforming Financial Verticals
Moving toward an AI-native model looks different in each part of the industry. Every vertical handles distinct data, answers to different regulators, and defines value in its own way. Across trading floors, underwriting desks, payment networks, and compliance teams, AI is changing how work gets done.
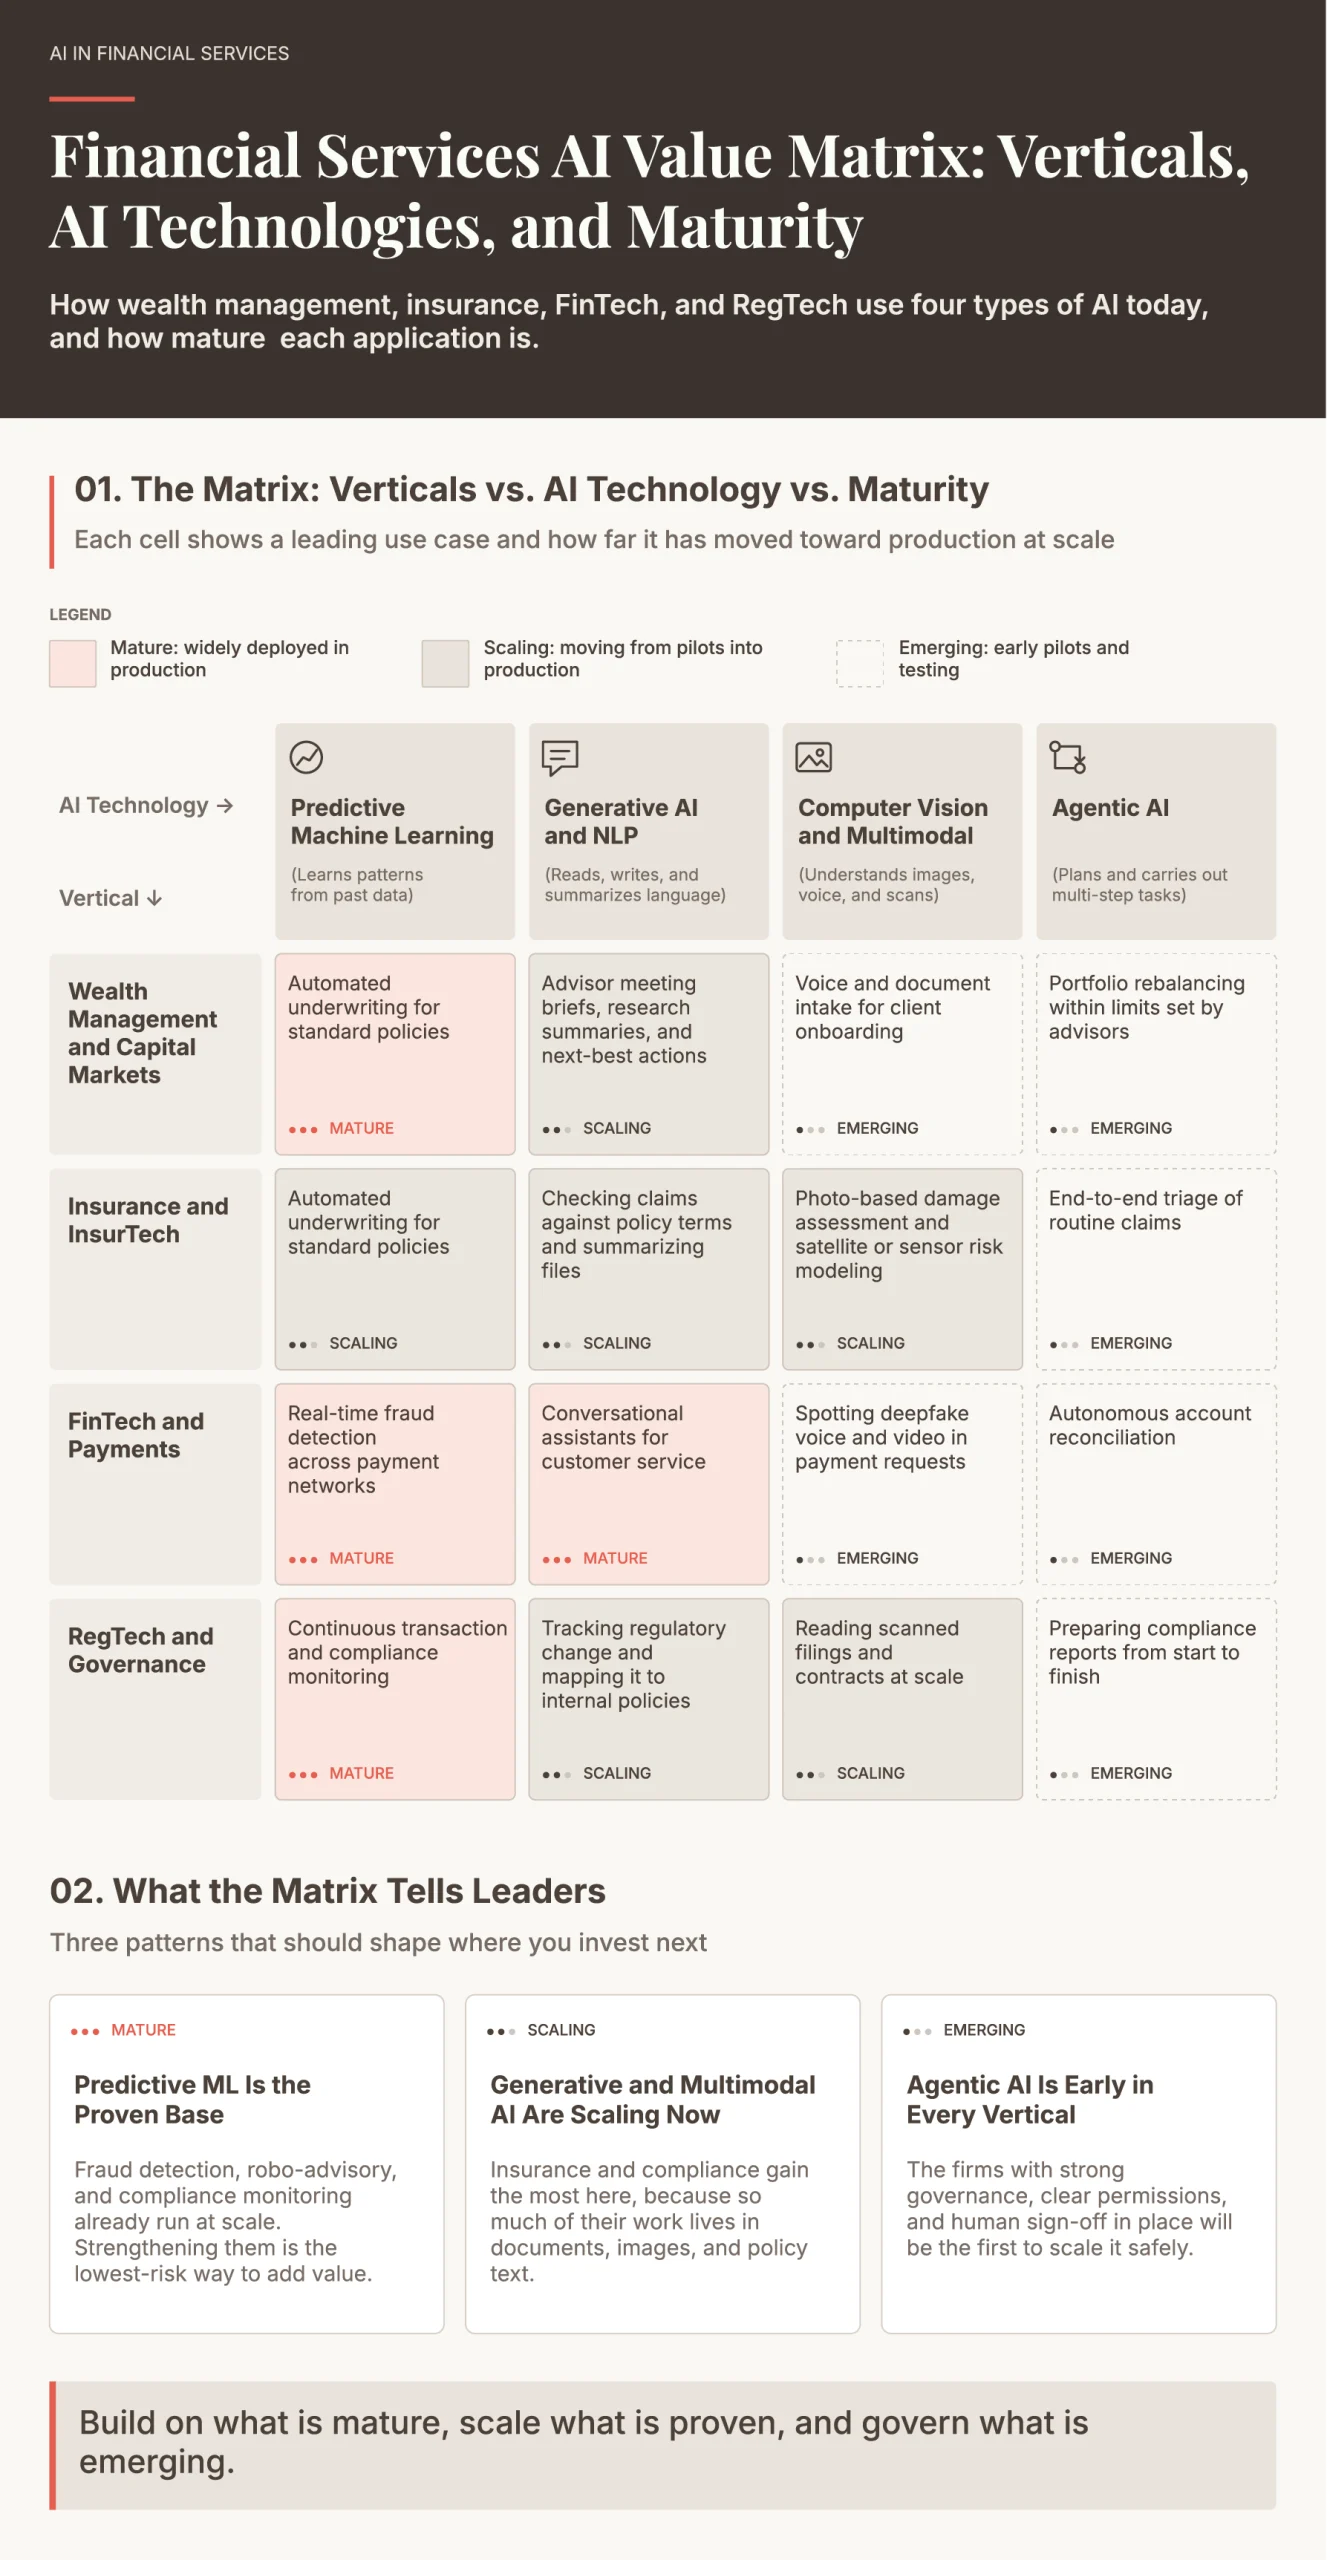
The matrix below maps these verticals against the AI technologies they use and their current levels of maturity.
I. Wealth Management and Capital Markets
Wealth managers and trading firms adopted these tools early. Their use of AI has matured from simple automation to prediction. Robo-advisors use AI to build automated portfolios based on a client’s risk tolerance and financial goals. They monitor and adjust these portfolios in real time, adapting to market shifts and keeping clients on track for their investment objectives. They have also drastically reduced the cost of financial advisory services, making personalized investment guidance accessible to a broader audience.
AI also helps with predictive portfolio rebalancing. Models forecast shifts in volatility or asset correlation and suggest adjustments before market drift harms returns. Additionally, AI assistants prepare briefs for meetings, summarize research, and suggest next-best actions for human advisors, freeing them to focus on client relationships.
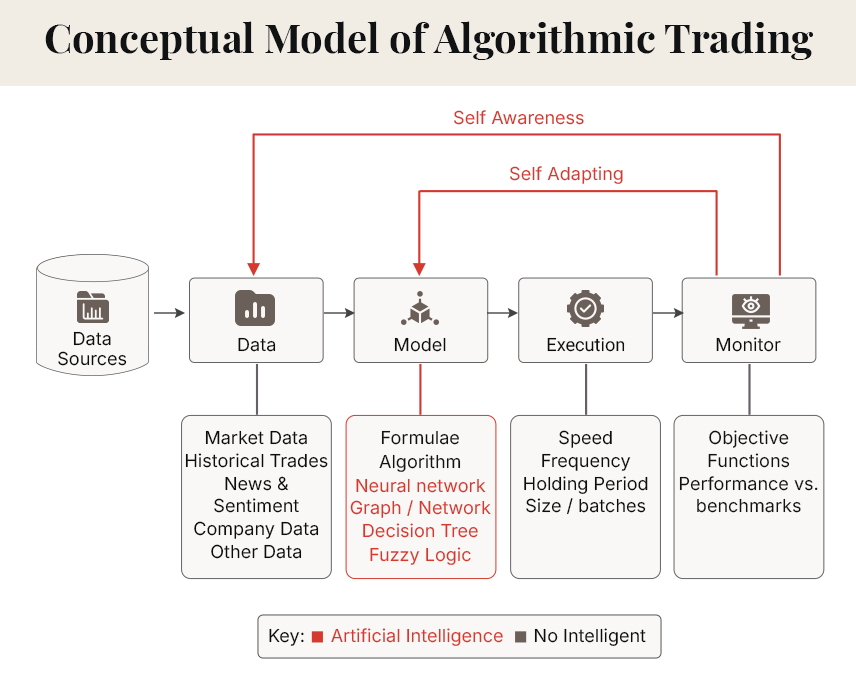
AI systems powered by complex mathematical models drive high-speed trades in capital markets. They process vast datasets instantly and detect trends in market data that human traders would likely miss. No wonder, the global AI trading platform market size is projected to reach $33.5 billion3 by 2030, growing at a CAGR of 20%.
II. Insurance and InsurTech
The insurance industry relies on assessing risk accurately, and that makes it a natural fit for AI. Automated underwriting models assess applications against a far wider set of data than a manual review allows. These systems process standard policies on their own and send only complex cases to human experts for review. Due to this, time to quote shortens, while human judgment stays focused where it adds the most value. Our blog on AI in insurance underwriting talks about this change in detail.
Claims are another opportunity. AI can assess photos of vehicle or property damage, compare each claim against policy terms, and flag anomalies for review. As a result, claims are settled much faster. On the risk side, satellite imagery, weather data, and readings from sensors let insurers model property and catastrophe exposure with far more accuracy than annual inspections could.
III. FinTech and Payments
Digital payments move quickly and often cross international borders. This makes fraud detection a highly valuable use case of AI in financial services. Older fraud detection systems used rigid rules, which may lead to false positives or missed threats.
Machine learning algorithms now analyze large amounts of transaction data in real time and spot anomalies that human eyes might miss. For a global payment network, AI can identify a suspicious transaction, like an unusually large payment from a foreign location. It also learns new fraud patterns continuously.
Credit represents another area of application. Traditional credit scoring methods often exclude individuals with limited credit history, even if they are financially responsible. AI is changing that by analyzing alternative data sources, such as utility payments and rental history, to provide a more complete view of creditworthiness. Companies like Upstart are using AI to offer credit to individuals who may have been denied by traditional lenders.
IV. RegTech and Governance
The financial services sector runs under strict regulatory oversight, with compliance requirements that evolve regularly. RegTech tools use AI to track regulatory updates across jurisdictions, map new requirements to internal policies, and alert the teams who need to act. They also automate compliance monitoring and reporting, so issues surface continuously rather than at quarter-end. Also, every automated check creates an audit trail. This gives regulators a clear record of what was reviewed and why.
The same capabilities boost enterprise risk management. By analyzing complex datasets that include market volatility, client behaviors, and even geopolitical events, AI systems can simulate various risk scenarios, helping institutions prepare for everything from economic downturns to unexpected shifts in customer behavior. Banks also use these tools for their KYC and anti-money laundering programs, a topic we cover in our guide to AI in banking operations.
Strategic Framework: Five Steps to Scale AI Across Financial Institutions
The above use cases show what AI can achieve. But they do not explain why so many institutions find it difficult to move past the pilot stage. Many times, the real challenge is not the model, but everything that surrounds it, including data, architecture, and governance.
The following steps separate the firms that scale AI from those that remain stuck in proofs of concept.
Step 1: Unify Data and Modernize Infrastructure
Financial institutions run on systems that were not built for modern AI workloads. Customer, transaction, and risk data generally sit in separate platforms, with different formats and owners. Until companies unify that data, every AI project must rebuild the same data pipelines. This explains why 75%4 of institutions remain stuck with siloed pilots.
A good solution is to build API integration layers that connect AI capabilities to legacy systems. This removes the risk of trying to replace everything in one go. Institutions can then modernize their core platforms in phases with support from legacy modernization services.
Step 2: Select Domain-Specific Models
With reliable data in place, leaders must decide which models to use. Proprietary LLMs offer a broad range of capabilities. But they raise concerns around cost, data residency, and dependence on a single vendor. Open-source models give institutions more control and can be fine-tuned on internal data. Small language models trained for a narrow task, such as classifying claims, often match larger models on accuracy at a fraction of the running cost.
A lot of organizations use a combination of all three. The build-versus-buy decision follows the same logic. Buy standard industry capabilities and build custom solutions for the workflows that give your institution a competitive edge.
Step 3: Establish Governance and Ethical Frameworks
Once models start influencing key decisions, governance is what keeps them trustworthy. Teams must test models for bias before and after deployment, use explainable AI to trace how decisions are made, and maintain a complete model inventory with named owners.
Regulation sets the minimum standard. The EU AI Act treats two financial uses of AI as high-risk: assessing an individual’s creditworthiness and pricing life and health insurance based on risk. Systems in these categories must meet strict requirements for data quality, documentation, and human oversight. In the US, the SEC has taken enforcement actions against advisors that overstated their AI capabilities.
Step 4: Keep Humans in the Loop
Governance also needs to define where complete automation should stop. Human-in-the-loop design keeps experts involved in critical decisions, such as large credit approvals or claim denials. Low-risk tasks run on their own, whereas edge cases go to a person with the context to make decisions.
That way, AI can handle analysis and automation while humans focus on advice, relationships, and complex judgment calls. Getting this balance right protects customers. It also gives employees the confidence to use the system.
Step 5: Measure Enterprise ROI
The final step is to measure true returns, because simply adopting AI does not guarantee business value. In fact, Gartner’s5 2025 survey of 183 CFOs and senior finance leaders found that 59% use AI in their finance function, yet 91% report only low or moderate impact.
Part of that gap comes from measuring success narrowly. Though cost savings matter, return on investment should also factor in market share growth, customer lifetime value, total cost of ownership, and time to market new products. Studying these metrics before and after launching a project makes it easier to determine which pilots should be scaled.
Who Owns What: The CIO, CTO, and CDO Roles
None of these steps succeed without clear ownership at the top. The CDO typically owns data quality, lineage, and access policies. The CTO owns the architecture, the model platform, and integration with core systems. The CIO ties technology investment to business priorities and governs the portfolio of AI initiatives, while the CEO and board set the institution’s risk appetite. When these roles are agreed early, AI decisions move faster because everyone knows who signs off and who answers for the results.
Build an AI Roadmap Your Regulators Can Trust
Key Challenges and Risk Management in Financial AI
There is a version of the AI story in financial services that glosses over the hard parts. This is not that version. Because if you are a leader trying to make a real decision about AI investment and deployment, you need to know what you are walking into.
These are the challenges that slow institutions down, along with what actually helps.
I. Sensitive Data
AI needs data. Lots of it. And in financial services, that data is among the most sensitive there is, including transaction records, credit histories, identity documents, and behavioral patterns. Every data input is also a potential exposure point.
The Solution: Build a data minimization mindset. Share only the information the model genuinely needs. Pair that with end-to-end encryption, strict access controls, and regular third-party security reviews. Many institutions are also shifting towards private or hybrid cloud environments, specifically to keep sensitive data off public AI infrastructure.
II. Legacy System Integration
Integrating AI into core banking systems built in the 1990s is genuinely difficult. Anyone who tells you otherwise is selling something. The cost and complexity of connecting old technology to new models are primary reasons why many AI initiatives stall during the pilot stage.
The Solution: Avoid trying to overhaul everything at once. Start with high-value, lower-complexity use cases, like fraud detection and customer service. Connect the new AI tools to legacy systems through APIs.
III. Algorithmic Hallucination and Model Drift
Generative models can produce confident answers that are completely incorrect, a phenomenon called hallucination. A single invented figure in a client letter or regulatory filing can create real liability. Predictive models face a quieter issue called model drift. As markets and customer habits change, models trained on older data slowly lose accuracy without showing any obvious failure.
The Solution: Ground generative AI tools in verified internal sources, require citations for factual outputs, and keep human reviewers on anything that leaves the institution. For predictive models, track performance continuously against established thresholds and retrain the system when accuracy drops.
IV. AI-Specific Cybersecurity Threats
AI opens new entry points for bad actors. Prompt injection can trick a generative system into leaking data or ignoring safety rules. Data poisoning, on the other hand, corrupts training sets so that a model learns incorrect patterns. Deepfake audio and video are already being used to impersonate executives and customers in payment fraud. Furthermore, sharing data with external AI tools can expose proprietary information.
The Solution: Treat every AI system as part of the attack surface. Test models against security threats before release, limit the data and tools each AI agent can access, and add extra verification steps for high-value instructions received through voice or video.
The Complete Guide to Building Enterprise AI Agents
The Future Outlook: What’s Next for AI in Financial Services
Artificial intelligence is no longer a distant concept for the financial world. It is here and is reshaping everything from everyday banking to complex market operations. With the risks in view, here is where the industry is likely to head over the rest of the decade.
1. Autonomous Financial Agents Take on Routine Work
Within a few years, AI agents will likely handle routine financial tasks from start to finish, such as reconciling accounts, preparing compliance reports, or rebalancing portfolios within limits set by humans. Building them safely requires clear permissions, robust audit trails, and mandatory human sign-off on critical decisions.
2. Quantum-Assisted Machine Learning Improves Risk Modeling
Quantum computing is still at an early stage, but several large banks are already testing quantum-assisted machine learning for portfolio optimization and complex risk simulation. If the hardware matures as expected, calculations that take hours on classical systems, such as large Monte Carlo runs, could be completed much faster.
3. Hyper-Personalized Products Arrive in Real Time
Combining open banking data, real-time analytics, and generative AI will allow institutions to tailor financial offers the moment a customer’s situation changes. For example, a savings plan could adjust automatically following a salary raise.
Conclusion
AI is reshaping every part of the financial services industry. Institutions using it thoughtfully see real results. Those that struggle tend to underestimate what responsible AI requires, including unified data, governance, bias monitoring, and culture change. These challenges are surmountable with serious leadership.
The key question isn’t whether to invest in AI, as that debate is over. Instead, ask, “Are we building AI capability that will still give us an advantage in five years, or just reacting to competitors?” Institutions answering this honestly will define the future of finance, while others will spend the decade catching up.
References:
Frequently Asked Questions
Artificial intelligence in financial services refers to the enterprise deployment of machine learning, natural language processing, and generative AI across wealth management, capital markets, insurance, and banking. It enables real-time risk assessment, predictive portfolio management, automated regulatory compliance, and personalized customer experiences. Institutions deploying enterprise AI realize operational efficiency gains and reductions in risk exposure.
Returns vary by use case and maturity. In NVIDIA's6 2026 survey, 64% of financial services respondents said AI raised annual revenue by more than 5%, and 61% said it cut annual costs by more than 5%. Returns are strongest when institutions measure value beyond cost savings, including customer lifetime value, market share, and time to market.
In wealth management, the main use cases include robo-advisory, predictive portfolio rebalancing, and AI assistants that prepare advisors for client meetings. In insurance, they are automated underwriting, AI-assisted claims assessment, and risk modeling that uses satellite and sensor data.
Look for firms that are transparent about how they use AI, have clear data privacy policies, offer human review for significant decisions, and are regulated by a recognized financial authority. Responsible AI use should be visible in a firm's communications and governance practices, not buried in fine print. Companies should also use explainable AI (XAI) to detect and avoid algorithmic bias.
Financial services firms look for AI partners with strong data security, regulatory compliance knowledge, proven reliability, and transparent (explainable) AI systems. Industry experience, scalability, and the ability to integrate with existing infrastructure are also essential. A clear ethical framework and responsive ongoing support are equally important considerations.


