Executive Summary:
- AI in banking operations helps banks reduce manual hand-offs across high-volume back-office and middle-office workflows, including customer due diligence, lending, reconciliation, and dispute management.
- Intelligent document processing, machine learning, and workflow orchestration can shorten cycle times and improve data consistency when integrated with core banking systems and clear exception rules.
- Operational value should be measured through cycle time, cost per completed case, straight-through processing, exception rates, false positives, and audit completeness. Human review remains essential for material or ambiguous decisions.
Imagine a customer applying for a loan. A few years ago, the process might have involved submitting stacks of documents, waiting for verification, and following up with the bank for an update. Meanwhile, operations teams manually checked records, reconciled data across systems, and flagged discrepancies for review. Today, AI in banking operations can help banks extract information from documents, identify inconsistencies, detect suspicious transactions, and route cases to the right teams faster.
This shift is gaining momentum. A 2026 global study by the Cambridge Center for Alternative Finance1 found that 81% of surveyed financial services firms were adopting AI, while 40% reported advanced adoption. The findings reflect how AI is moving beyond experimentation into practical financial services workflows.
For banks, the opportunity extends beyond faster customer service. AI can streamline back-office operations, support KYC and anti-money laundering (AML) checks, accelerate loan processing, and improve reconciliation. This guide explores the key AI technologies, banking process automation use cases, implementation approaches, and operational metrics banks can use to evaluate performance and measure return on investment.
How is AI Used in Banking Operations?
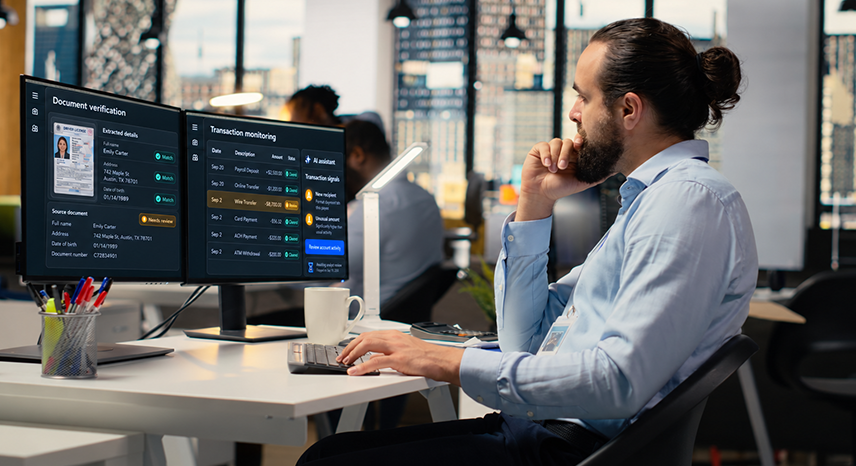
AI in banking operations applies machine learning, natural language processing, intelligent document processing (IDP), and generative AI to specific workflows. It can extract data from financial documents, compare records across systems, prioritize exceptions, draft case summaries, and route work to the right team. Banks should distinguish decision support from autonomous decision-making: AI can prepare evidence and recommend next steps, while authorized staff retain control over regulated or high-impact outcomes.
The 2026 Grant Thornton banking AI survey2 reports that 62% of banks surveyed see greater efficiencies from AI, while 42% cite insufficient data readiness as a cause of project failure. These findings point to a practical priority: automate defined workflows with reliable data and measurable controls rather than deploying AI as a stand-alone layer.
What are the Key AI Technologies Used in Banking?
Banks use specific AI technologies to improve services and operations. Explore the key technologies from machine learning to Generative AI that transform how banking works.
| AI Technology | Workflow Improved | Productivity Outcome |
|---|---|---|
| Machine Learning | Fraud detection |
|
| Natural Language Processing | Customer service and onboarding |
|
| Robotic Process Automation | Loan processing and compliance |
|
| Predictive Analytics | Credit risk assessment |
|
| Generative AI | Personalized marketing |
|
| Anomaly Detection | Anti-money laundering screening |
|
What are the Operational Bottleneck in Legacy Banking?
Banking operations often depend on multiple systems that were implemented at different times. A loan application may move between document repositories, credit platforms, customer information files, and a core banking system. KYC analysts may need to reconcile inconsistent customer details across onboarding, sanctions screening, and transaction monitoring tools. Finance teams may compare entries across ledgers and payment platforms using spreadsheets.
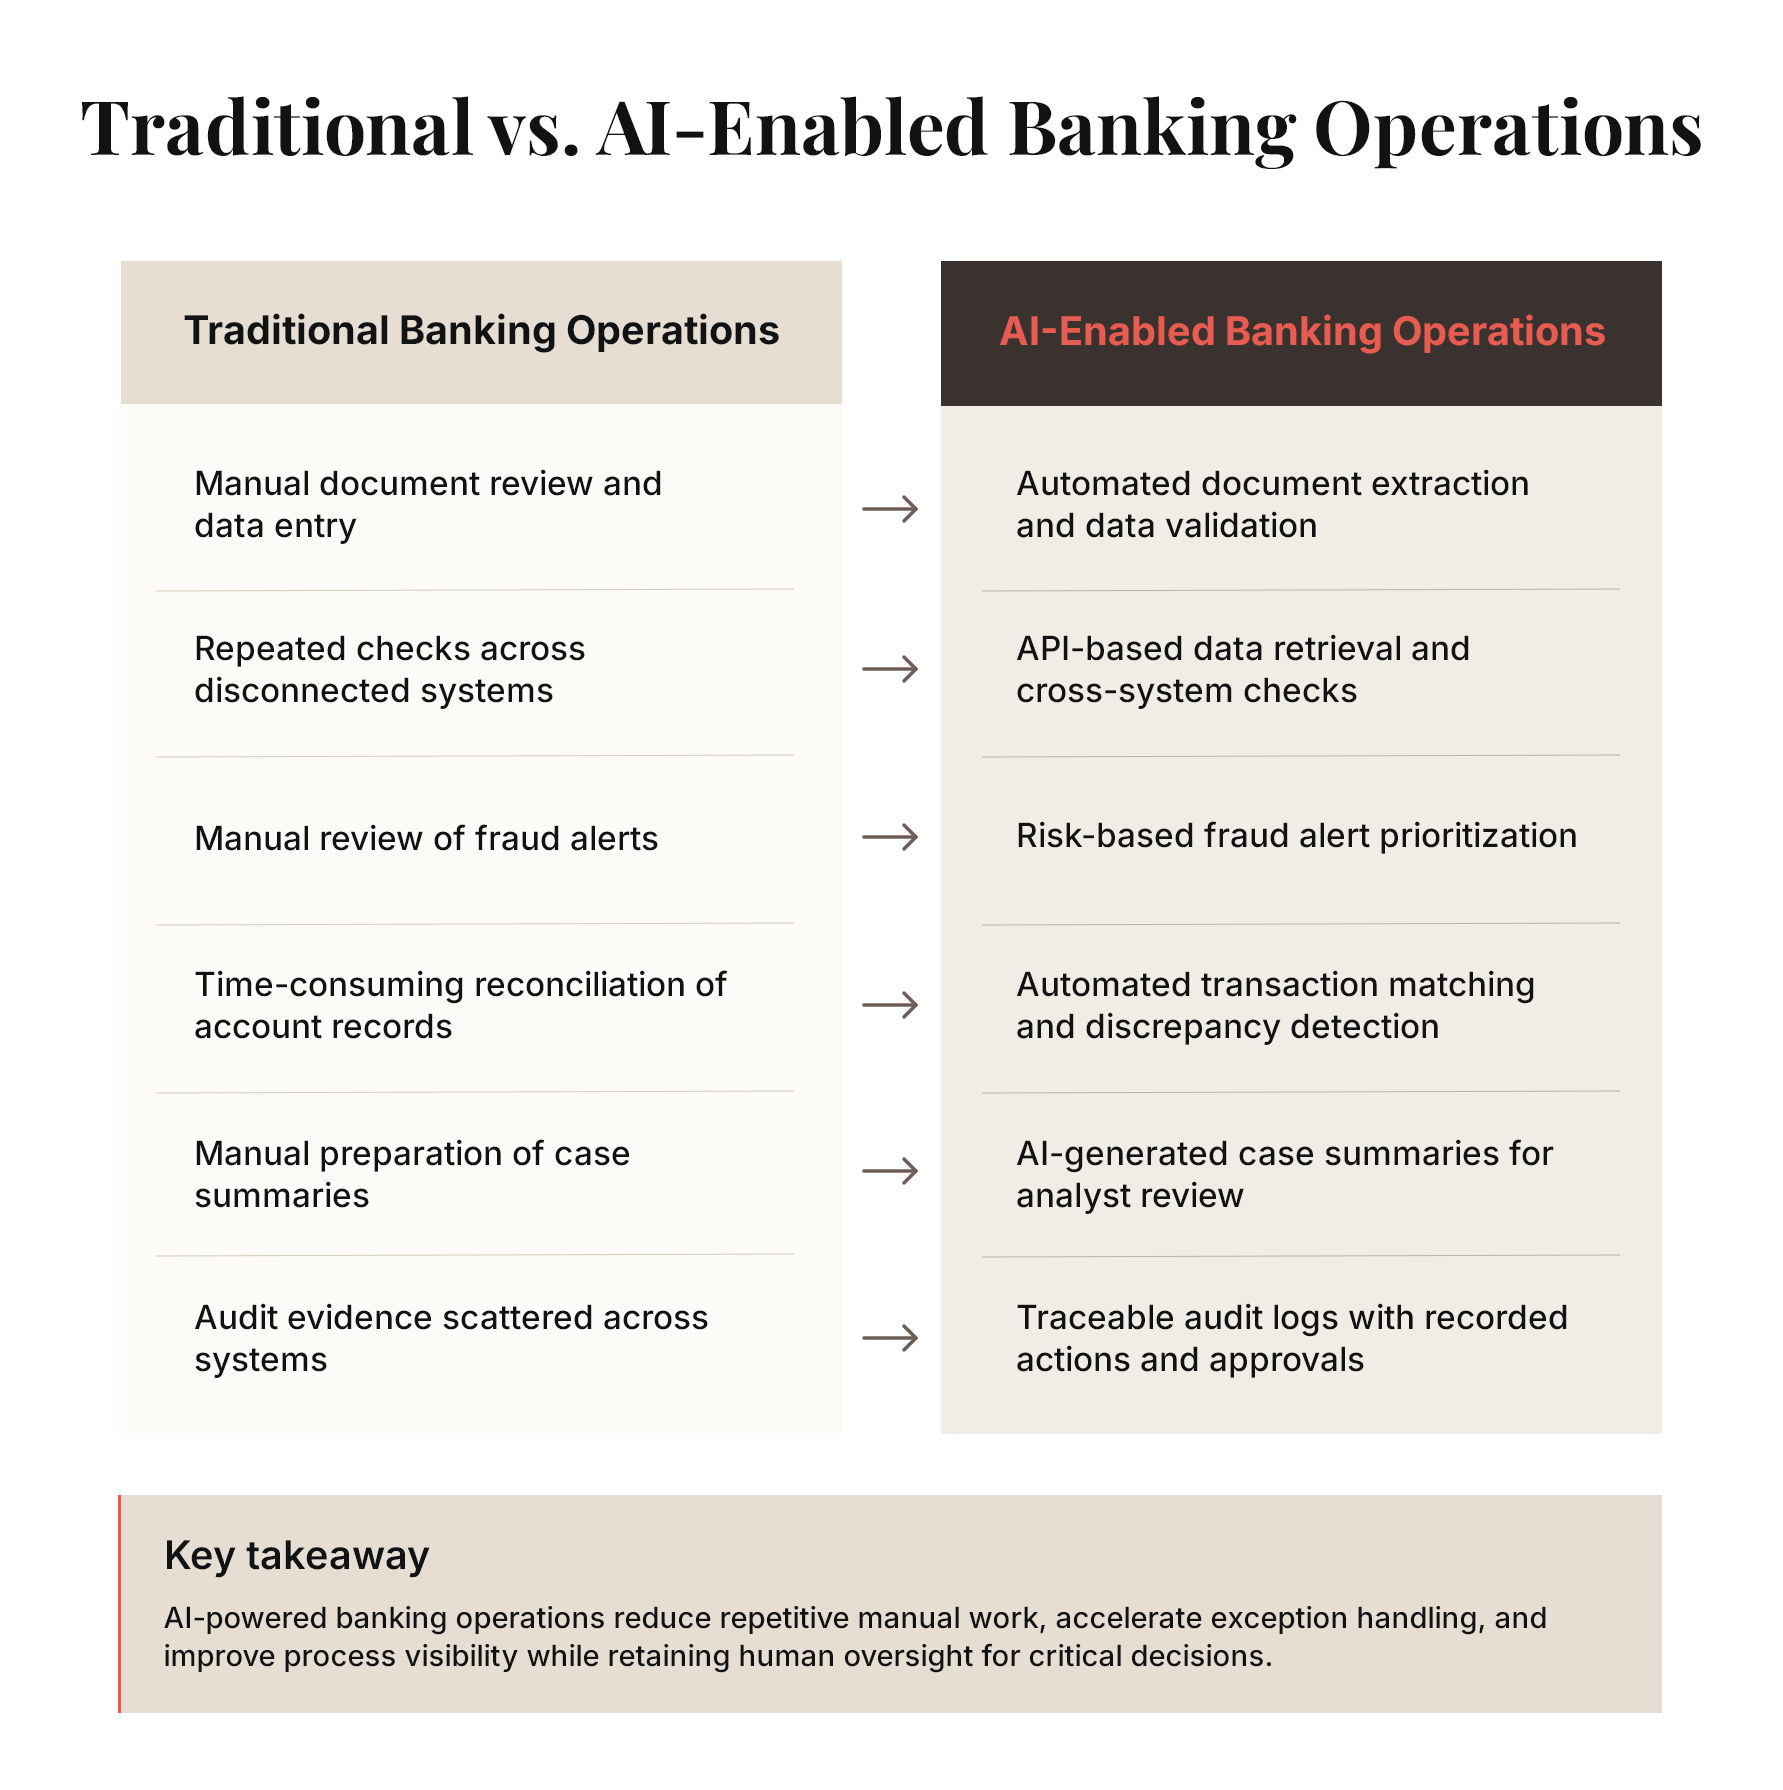
These hand-offs create delays, duplicate data entry, rework, and limited visibility into case status. The impact is measurable: longer onboarding and loan turnaround times, higher cost per case, missed service-level agreements, and more analyst time spent on routine checks instead of complex exceptions.
A 2025 WorkFusion and 1LoD financial-crime benchmarking survey3 found that 94% of participating banks identified high manual workloads as a primary AML/KYC challenge, and 60% said more than half of their AML/KYC processes still required manual intervention. The findings make KYC and AML strong candidates for targeted banking process automation.
What are the Key Benefits of AI in Banking?
AI creates measurable benefits that transform banking operations and experiences. Discover the essential advantages, from better efficiency to significant cost savings, that make AI valuable in banking.
- Improved Efficiency: Automates routine tasks, freeing up human resources for more complex activities.
- Better Accuracy: Reduces errors and improves decision-making processes.
- Significant Cost Savings: Lowers operational costs by automating processes and reducing the need for manual intervention.
“AI will affect virtually every function, application and process in the company. And in the long run, it will have a huge positive impact on productivity”
– Jamie Dimon, Chairman & CEO of JPMorgan Chase.
What are the High-Impact Use Cases of AI in Core Banking Operations?
AI delivers the greatest value in core banking operations by automating repetitive tasks, improving accuracy, and accelerating decision-making across back-office and middle-office workflows. Key use cases include KYC/AML compliance, loan origination, trade finance document processing, fraud investigation, dispute resolution, and financial reconciliation.
1. End-to-End KYC and AML Workflow Automation
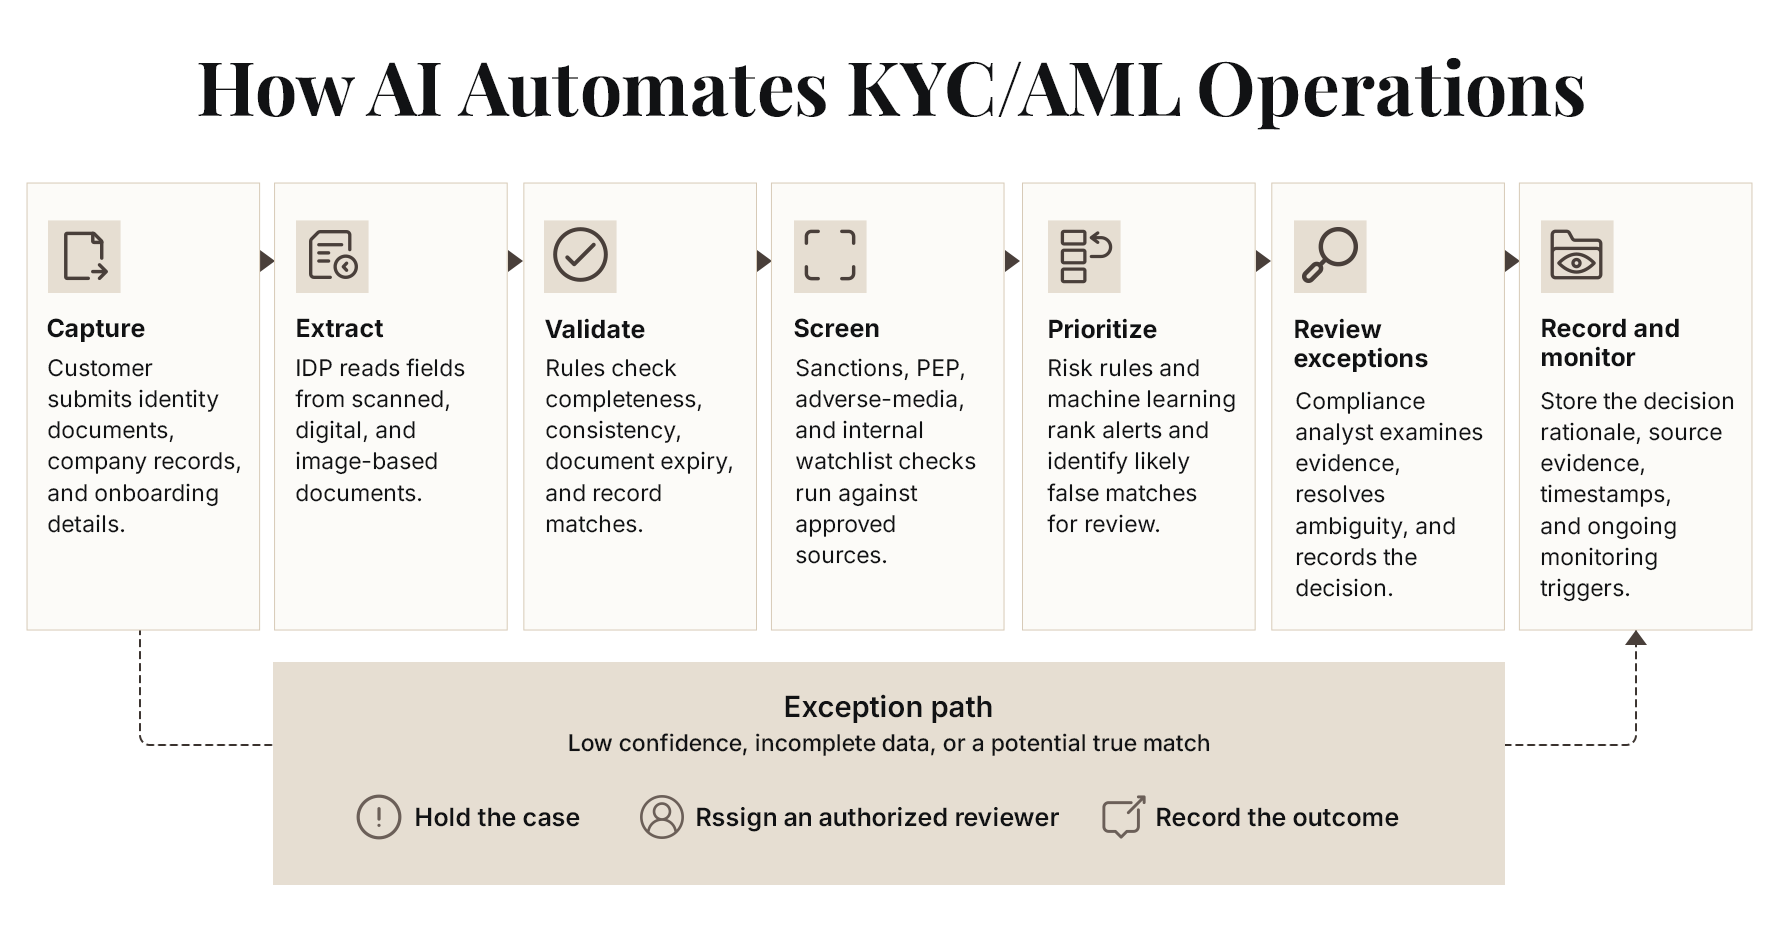
An AI-enabled KYC workflow can collect identity documents, extract names and dates, validate required fields, compare customer details against internal records, and route potential matches for review. Machine learning can help prioritize alerts based on risk signals, while generative AI can prepare a concise case summary from approved evidence for an analyst.
A controlled workflow typically follows these steps: capture documents and customer data; validate completeness and authenticity; screen against sanctions, politically exposed person, and adverse-media sources; compare potential matches; assign a risk score; route exceptions to compliance staff; and preserve the evidence and rationale in an audit trail. AI should not automatically dismiss material alerts without approved controls and documented thresholds.
2. Intelligent Loan and Mortgage Origination
Intelligent document processing in banking can extract income, employment, liabilities, account balances, and other fields from bank statements, tax documents, pay slips, and application forms. Validation rules can compare extracted values with application data, flag missing documents, identify inconsistencies, and assemble a structured case file for an underwriter.
An AI loan origination system can also summarize supporting documents and explain why a case needs attention. Credit decisions must remain aligned with approved underwriting policy, fair-lending requirements, and explainability standards. Route low-confidence extractions, conflicting figures, and policy exceptions to human reviewers instead of treating model output as verified fact.
A 2026 study from Abrigo4 reported that 79% of surveyed institutions had AI pilots or AI integrated into lending workflows, and 78% identified faster loan decisions as a top expected benefit. The same study found that 58% cited privacy, cybersecurity, or confidential-information risks as a leading concern.
3. Trade Finance Document Processing
Trade finance teams process letters of credit, bills of lading, commercial invoices, packing lists, certificates of origin, and other documents. IDP can classify each document, extract structured fields, and compare quantities, dates, parties, shipment details, and amounts across the document set. Rules can flag missing documents, inconsistent values, or discrepancies against letter-of-credit terms.
The system should create a discrepancy queue with the source document, extracted field, rule triggered, and confidence score. Trade operations specialists then resolve exceptions. This approach reduces repetitive comparison work without removing the need for expert judgment on documentary discrepancies and applicable trade rules.
4. Fraud Investigation and Incident Orchestration
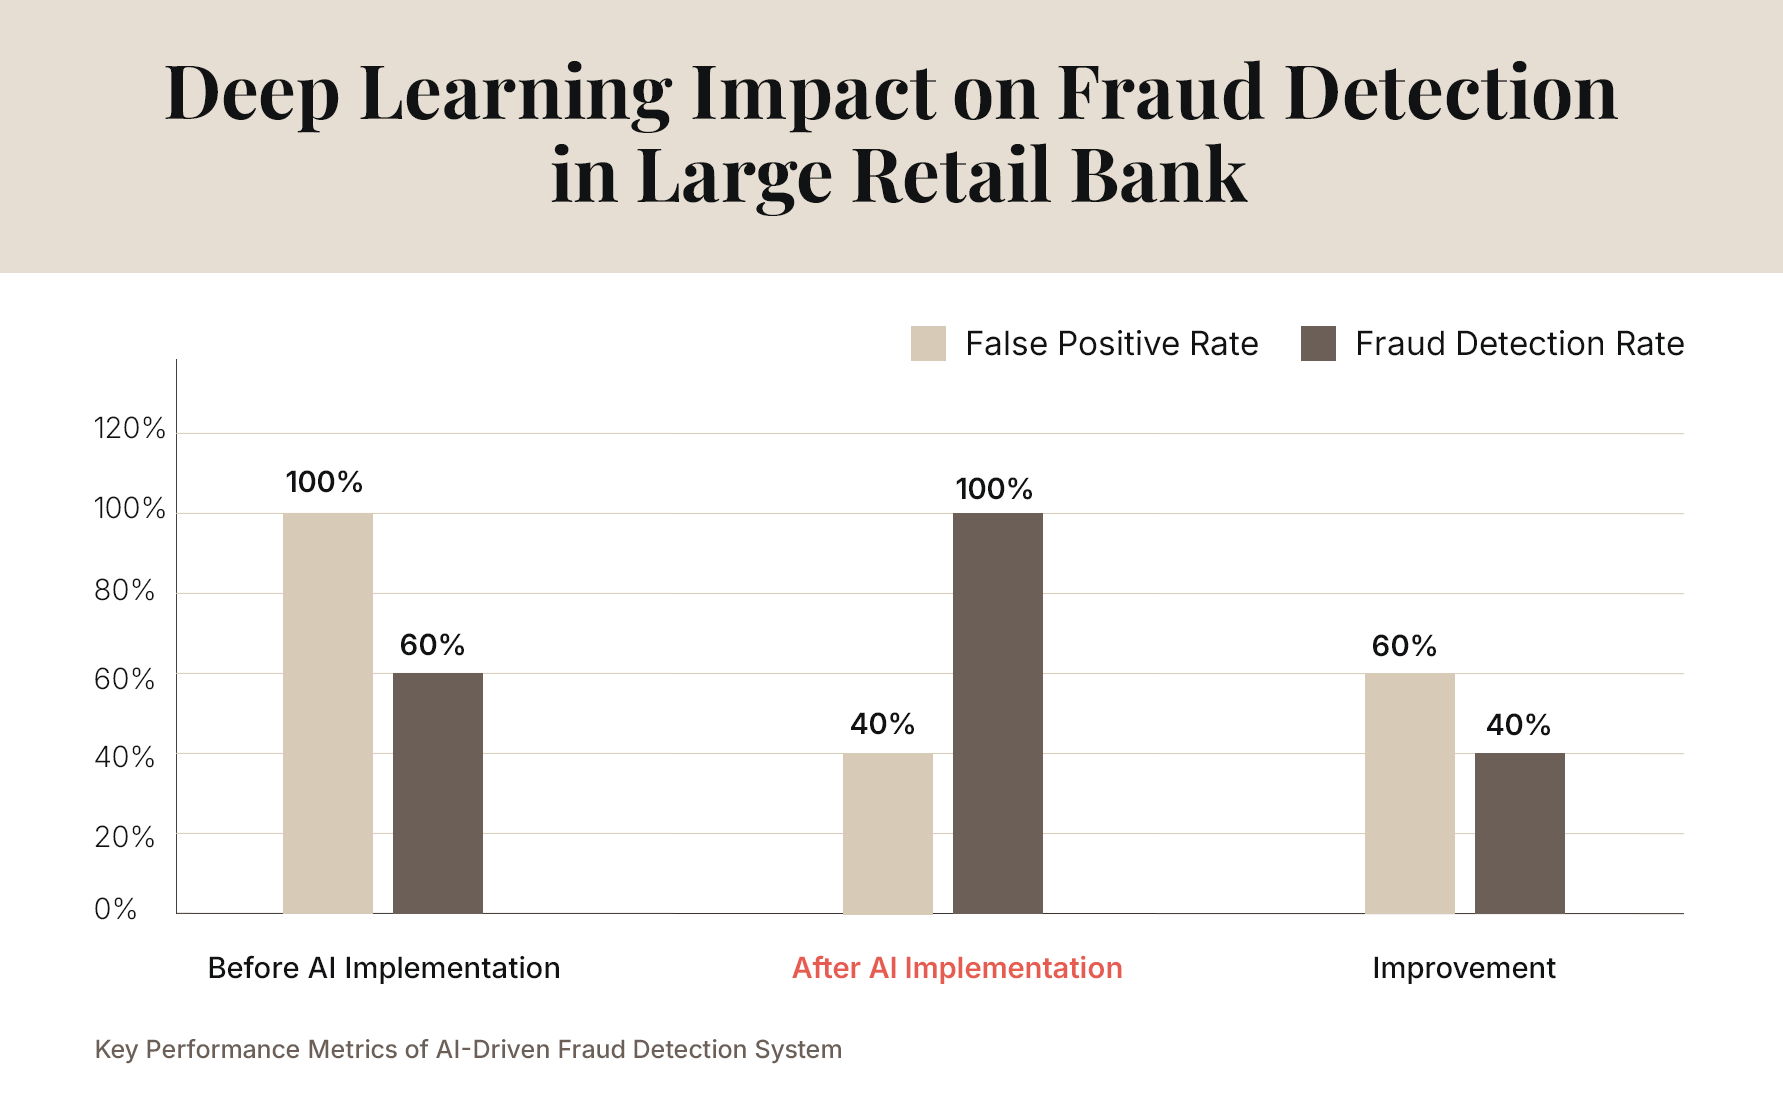
Fraud detection is one of the most critical applications of AI in banking. AI systems can analyze vast amounts of transaction data in real-time to identify suspicious activities. Behavioral biometrics, like typing patterns or device usage, add another layer of security, differentiating genuine customers from imposters. By recognizing patterns and anomalies, AI can detect fraudulent transactions before they cause significant damage. For instance, HSBC’s use of AI for voice recognition has significantly reduced phishing attempts, setting new benchmarks in fraud prevention.
5. Card Dispute and Chargeback Handling
AI can classify incoming disputes, extract transaction details, check submission deadlines, retrieve relevant receipts or delivery records, and assemble evidence against the applicable card-network reason code. Workflow rules can route incomplete cases to the right team and track deadlines through representment and settlement.
Automation should not submit unsupported claims or infer evidence that does not exist. A reviewer should approve complex, high-value, or low-confidence cases. Useful KPIs include time to first action, evidence completeness, representment success, avoidable write-offs, and cost per dispute.
6. Financial Close and Account Reconciliation
AI-supported reconciliation can match transactions across bank statements, payment systems, sub-ledgers, and general-ledger entries using exact identifiers and configurable fuzzy-matching rules. The system can group unmatched entries, identify likely causes, prioritize material differences, and draft proposed journal-entry descriptions for review.
Keep posting permissions separate from analysis and recommendation. Finance teams should approve journal entries according to existing controls, and every match or adjustment should retain source references, rule versions, timestamps, and reviewer actions. Track auto-match rates, aged breaks, close-cycle duration, rework, and unresolved balances.
7. Branch and Contact Center Operational Support
AI assistants can retrieve approved procedures, summarize customer interactions, classify requests, suggest next actions, and populate case records. Speech-to-text and summarization can reduce after-call work, while routing models can direct requests based on intent, urgency, and required expertise.
The assistant should retrieve from approved knowledge sources, disclose uncertainty, and escalate requests involving suspected fraud, complaints, vulnerable customers, or exceptions to policy. Measure average handling time alongside first-contact resolution, quality assurance scores, escalation rates, and repeat contacts. Faster responses alone do not prove better service.
Banks can extend these capabilities through conversational AI chatbot development. These chatbots handle routine customer queries, provide account-related assistance, and route complex requests to the appropriate teams.
How to Build Smarter Virtual Assistants with Conversational AI Chatbot Development
How Can Banks Integrate AI with Core Banking Systems?
AI in banking operations requires secure integration with existing core banking systems, reliable document processing, and data validation. An API-first approach helps banks automate workflows while maintaining data accuracy, system interoperability, and regulatory auditability.
Step 1: Connect Through APIs and Controlled Adapters
Map the systems that own customer records, accounts, lending cases, payments, general-ledger entries, and compliance decisions. Use supported APIs, event streams, or controlled adapters to exchange only the data needed for each workflow. Integration patterns vary across FIS, Fiserv, Temenos, Jack Henry, and bank-specific platforms, so confirm product version, API availability, licensing, and vendor constraints before designing connectors.
For more complex workflows, build enterprise AI agents that can coordinate tasks across connected banking systems, retrieve relevant information, and support multistep processes under defined controls.
Step 2: Establish Document Intelligence and Data Validation
Use OCR and multimodal document models to classify files and extract fields from forms, tables, scans, and image-based records. Apply deterministic checks for required fields, valid formats, arithmetic consistency, and cross-document matching. Store confidence scores and the original source location for each extracted value so reviewers can verify it quickly.
Step 3: Orchestrate Multi-Step Workflows
Use workflow orchestration to sequence extraction, validation, screening, case creation, approvals, and downstream updates. Generative AI in banking operations can summarize evidence and propose next steps; conventional rules should control eligibility, thresholds, permissions, and required approvals. Agentic AI should operate within narrowly defined tool permissions and must not bypass approval gates.
Step 4: Build Human Review and Audit Trails into the Process
Define which cases can proceed automatically and which require review. Trigger human intervention for low-confidence extraction, conflicting records, material financial differences, suspected sanctions matches, policy exceptions, and model uncertainty. Log the input sources, model and rule versions, actions taken, approvals, and final outcome. Apply access controls, encryption, retention rules, monitoring, and incident-response procedures.
Humans remain essential for validating AI outputs, securing core banking integrations, and maintaining reliable systems. Read more about why AI will not replace software engineers and how AI is changing their roles.
What are the KPIs for Measuring the ROI of AI in Banking?
Banks measure AI return on investment by tracking specific numbers that show how AI reduces fraud losses, speeds up loan approvals, cuts operating costs, improves customer satisfaction, and increases revenue through better recommendations.
Set a baseline before deployment and compare results across equivalent case types and volumes. Do not present illustrative targets as guaranteed outcomes. The figures below are measurement categories, not universal performance claims.
| Metric | How to Measure it | What it Reveals |
|---|---|---|
| Cycle time | Median and 90th-percentile time from case receipt to resolution | Whether the workflow moves faster, including exceptions |
| Cost per completed case | Labor, platform, integration, review, and exception-handling cost divided by completed cases | Whether total unit economics improve |
| Straight-through processing | Share of eligible cases completed without manual intervention | How much routine work can safely flow through automation |
| Extraction and matching quality | Field-level accuracy, match precision, and error rate from sampled cases | Whether automation is reliable enough for each workflow |
| False-positive rate | Share of alerts reviewed and found not to represent the targeted risk | Analyst workload and screening quality |
| Exception and rework rate | Share of cases returned, corrected, or escalated after initial processing | Hidden friction and poor source-data quality |
| Audit completeness | Share of sampled cases with complete evidence, decision rationale, and timestamps | Whether speed is achieved without weakening control |
How Should Banks Measure the Business Case for AI?
Calculate the business case at workflow level. Include implementation and integration costs, model and platform fees, data remediation, monitoring, human review, change management, and ongoing validation. Compare these costs with measurable reductions in handling time, rework, external processing costs, aged exceptions, and operational losses. Use a controlled pilot or matched comparison where possible, and separate realized savings from capacity released for other work.
A July 2026 survey by DA Davidson5, reported by S&P Global Market Intelligence, found that US banks expect AI adoption to reduce expenses by an average of 4.5% to 5% over the next two to three years, compared with anticipated revenue growth of 2.5% to 3%. However, only 11% of survey respondents said AI-related cost savings were measurable. This highlights why banks need clear baselines, workflow-level KPIs, and controlled pilots to validate actual returns rather than relying on projected efficiency gains.
How Can Banks Modernize Operations with Tailored AI-Powered Solutions?
What Are the Common Implementation Risks and Controls?
- Data Quality and Lineage: Confirm that customer, transaction, and document data are complete, current, and traceable to approved systems.
- Privacy and Security: Minimize data access, encrypt sensitive information, apply role-based permissions, and review third-party model handling.
- Model Quality: Test extraction accuracy, alert precision, bias, drift, and performance across representative cases before and after release.
- Human Accountability: Define named owners, escalation paths, approval thresholds, and override procedures for consequential decisions.
- Operational Resilience: Maintain fallback procedures for model outages, API failures, degraded data quality, and unexpected volumes.
- Auditability: Retain evidence, prompts, or workflow instructions where appropriate, rule and model versions, actions, and approval history.
“A strong AI strategy means clear ownership of data security, vendor management, and governance, so AI is built and run the same way across the bank.”
– Sameer Gupta, Americas Financial Services AI Leader, EY
What Is the Best Way to Start Banking Process Automation?
Start with a workflow that has high volume, clear rules, measurable delays, and manageable risk. Map the current process, identify exception types, define the baseline, and decide which steps can be automated safely. Pilot with a limited case segment, sample outputs for quality, and measure the end-to-end result rather than the speed of a single task. Expand only after operations, compliance, risk, and technology teams agree that controls and performance meet the required standard.
For banks modernizing legacy infrastructure, the objective is not to replace every core system at once. It is to connect AI capabilities to the systems of record, automate bounded tasks, and preserve the controls needed to explain and reconstruct every material action.
Summing Up
AI in banking has proven itself through countless successful implementations worldwide. The comprehensive guide covered everything from technologies to ROI measurement, giving banks practical tools for AI adoption that deliver measurable value rather than becoming another failed technology initiative wasting resources. Banks considering AI adoption may partner with a professional AI software development company to transform operations, while those treating it casually will struggle explaining why they waited so long.
References:
- 1. Cambridge
- 2. Grant Thorton
- 3. WorkFusion
- 4. Abrigo
- 5. S&P Global
Frequently Asked Questions
Banks combine IDP, machine learning, workflow automation, and APIs to extract information, validate records, prioritize exceptions, prepare case summaries, and update approved systems. Human review remains necessary for low-confidence cases and consequential decisions.
High-value starting points include summarizing KYC/AML case evidence, extracting and comparing loan documents, preparing trade finance discrepancy reports, explaining reconciliation breaks, and assisting operations staff with approved procedures. Generative AI should support controlled workflows rather than independently approve regulated outcomes.
An automated workflow captures customer documents, extracts and validates fields, screens approved watchlists, prioritizes potential matches, and routes exceptions to compliance analysts. Banks should preserve source evidence, decision rationale, timestamps, and ongoing monitoring triggers.
IDP combines document classification, OCR, machine learning, and language models to extract structured information from forms, statements, tax documents, invoices, and trade finance records. Validation rules and confidence scores help identify values that need human verification.
Track cycle time, cost per completed case, straight-through processing, extraction accuracy, false-positive rates, rework, operational losses, and audit completeness. Include integration, governance, monitoring, and human-review costs when calculating net benefits.
Yes, where supported interfaces and controls are available. Banks can use APIs, event streams, or controlled adapters to connect AI services with platforms such as FIS, Fiserv, Temenos, and Jack Henry. Integration design must be validated against the specific product, version, and bank architecture.


